Property Insurance Claim Help in a City With Many Different Kinds of Properties
Asbury Park is known for its beaches, music venues, restaurants, and historic architecture. But behind its familiar waterfront and downtown streets is a diverse collection of properties, each with different insurance claim concerns.
A Victorian-era home near Sunset Lake may require careful documentation of original building materials after a fire. A condominium near the oceanfront may involve questions about association coverage and individual unit-owner responsibilities. A restaurant on Cookman Avenue could face property repairs and lost business income after a significant water loss.
Main Street Adjusters helps Asbury Park homeowners, condominium owners, landlords, and commercial property owners navigate these situations.
We represent the policyholder, not the insurance company.
Our team evaluates property damage, reviews insurance coverage, prepares supporting documentation, examines claim estimates, and negotiates with carriers. The objective is to help property owners pursue a settlement that accurately reflects covered damage under their insurance policies.
From the Oceanfront to the West Side, Every Property Has Its Own Claim Considerations
Asbury Park is a compact city, but its buildings and neighborhoods vary considerably.
Near the boardwalk, residential and commercial properties are exposed to coastal weather. Downtown buildings may combine retail, restaurants, offices, and apartments. Established residential streets contain older single-family homes, duplexes, and multifamily properties. Newer residential developments introduce condominium associations, shared building systems, and different ownership arrangements.
The location and design of a building influence how damage occurs and how repairs should be evaluated.
Historic Homes and Established Residential Streets
Asbury Park’s older homes may contain original hardwood floors, plaster walls, decorative trim, older framing, and architectural details that require specialized attention after damage.
A fire, burst pipe, or roof leak can affect materials that are more complicated to repair or replace than standard modern finishes.
Renovated properties can present another challenge when older construction and newer building systems are affected by the same loss.
The insurance claim should identify what was damaged, what repairs are necessary, and how the applicable policy addresses those repairs.
Oceanfront Condominiums and Multifamily Buildings
Condominium and apartment properties may involve damage extending across several units or into common building areas.
A failed plumbing line can affect multiple floors. Roof or exterior damage may allow water into private residences and shared spaces. Fire and smoke can spread through corridors, mechanical systems, and neighboring units.
Coverage responsibilities may depend on the condominium association’s master policy, individual unit-owner coverage, or a landlord’s policy.
Main Street Adjusters helps policyholders document the loss and review which policy provisions may apply.
Coastal Storms, Roof Damage, and Flood Claims in Asbury Park
Asbury Park’s Atlantic shoreline and its proximity to Deal Lake, Sunset Lake, and Wesley Lake make the distinction between different causes of water damage especially important.
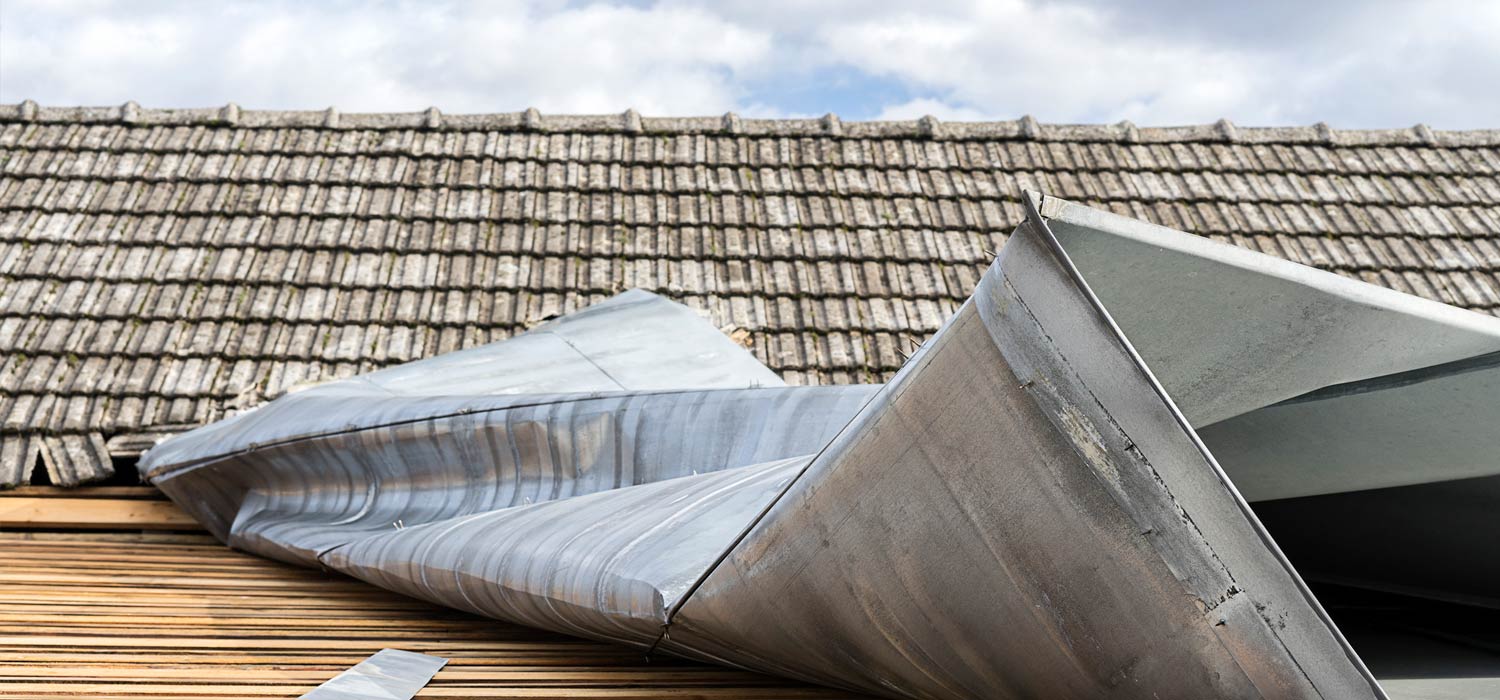
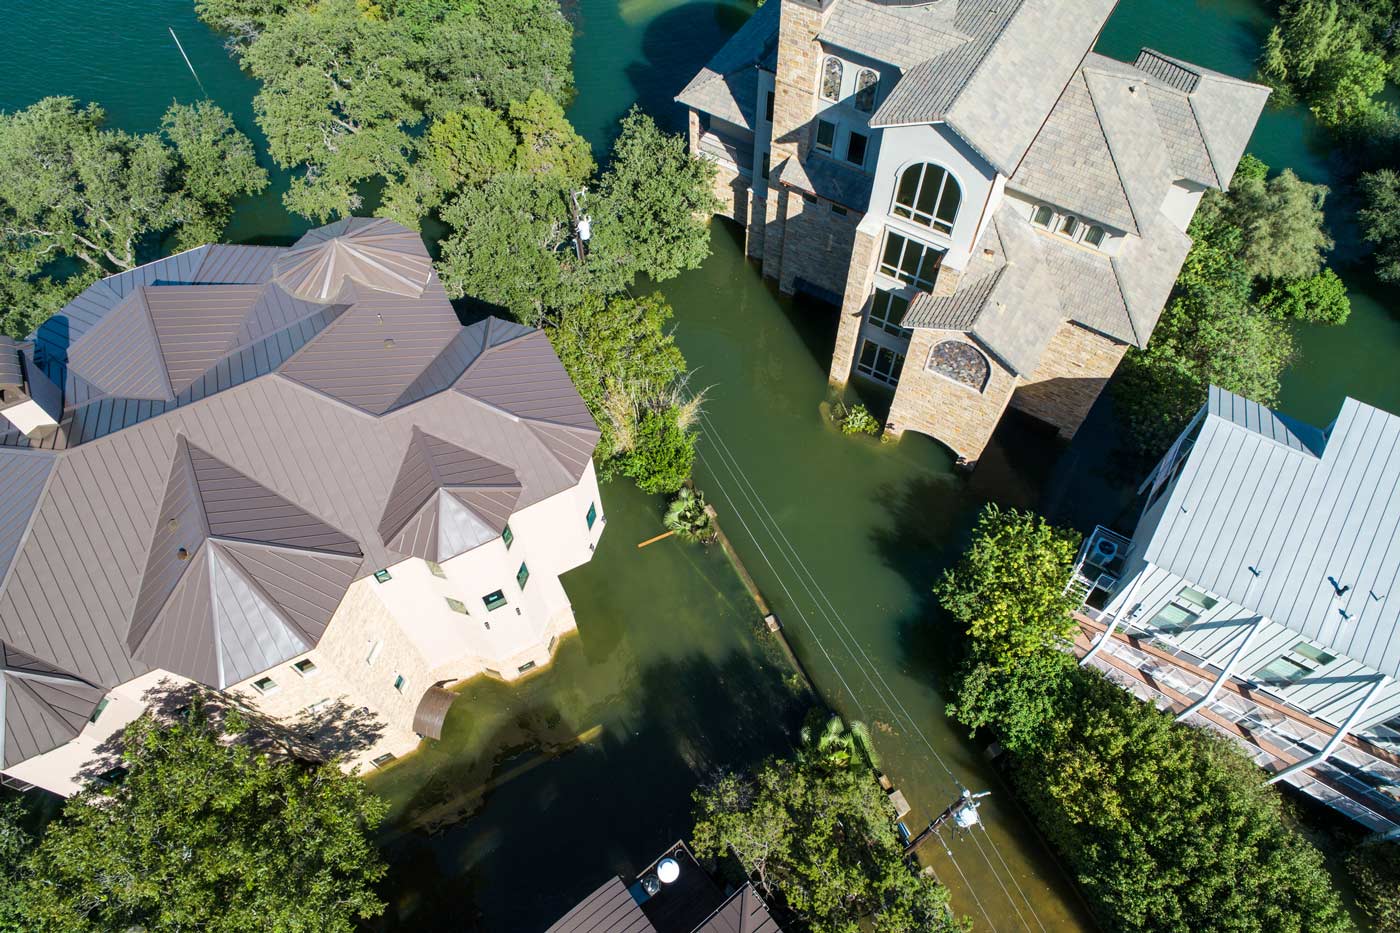
A coastal storm can produce wind damage, heavy rainfall, and flooding during the same event. Those losses are not necessarily covered under the same insurance provisions.

Fire and Water Damage in Asbury Park Homes and Businesses
Not every major property claim begins with a coastal storm.
An electrical fire, plumbing failure, appliance leak, or other unexpected incident can cause extensive damage to residential and commercial buildings throughout the city.


When Property Damage Disrupts an Asbury Park Business
Asbury Park has a distinctive commercial economy built around restaurants, music, entertainment, hospitality, retail, professional services, and year-round neighborhood businesses.
Commercial activity extends from the boardwalk and oceanfront to Cookman Avenue, Bangs Avenue, Main Street, Asbury Avenue, and Springwood Avenue.
For these businesses, property damage can have consequences beyond the physical repairs.
A restaurant may need to close following a kitchen fire. A hotel or lodging property may lose the use of rooms after water damage. A retail shop may experience damaged inventory and interrupted sales while repairs are completed.
Business interruption coverage may apply when qualifying covered physical damage causes an interruption that meets the policy’s requirements.
A claim may require financial statements, sales records, payroll information, continuing expenses, and documentation of the restoration period. Seasonal fluctuations can also be relevant when evaluating a business’s financial performance.
Main Street Adjusters assists commercial policyholders with documenting covered property damage and qualifying business income losses.
Asbury Park Neighborhoods and Districts We Serve
Main Street Adjusters assists property owners throughout Asbury Park, including but not limited to:
- Oceanfront and Boardwalk District: Ocean-view residences, condominium properties, hotels, restaurants, entertainment venues, and commercial spaces.
- Downtown and Cookman Avenue: Mixed-use buildings, restaurants, retail storefronts, offices, and residential properties.
- Bangs Avenue Corridor: Commercial properties, restaurants, offices, and nearby residential buildings.
- Sunset Lake Area: Established homes, multifamily properties, and residential streets near the lake.
- Deal Lake Area: Residential properties along the city’s northern boundary, including older homes and newer developments.
- Wesley Lake Area: Residential and commercial properties near the city’s southern boundary.
- Main Street Corridor: Retail businesses, service properties, offices, apartments, and mixed-use buildings.
- Springwood Avenue and the West Side: Established residential neighborhoods, community properties, commercial buildings, and redevelopment areas.
- Asbury Avenue Corridor: Residential buildings, neighborhood businesses, and commercial properties.
- Washington Avenue Area: Established residential streets with varied housing types.
- Northwest Asbury Park: Residential neighborhoods with single-family homes, duplexes, and multifamily properties.
- Southwest Asbury Park: Residential and community properties west of the downtown area.
We also assist property owners in other residential developments, condominium communities, and commercial locations throughout Asbury Park.
Our service area includes the entire city. Nearby communities such as Ocean Grove and Loch Arbour are separate municipalities.
Why Asbury Park Policyholders Work With a Public Adjuster
After a property loss, the insurance company’s adjuster evaluates the claim on behalf of the carrier. A public adjuster represents the policyholder’s interests.
Main Street Adjusters helps property owners develop an accurate, documented claim by reviewing the insurance policy, inspecting damage, preparing estimates, organizing supporting information, and examining the carrier’s assessment.
For historic homes, this may involve identifying damaged architectural materials and the appropriate repair scope.
For condominium owners, it may involve clarifying the responsibilities of different insurance policies.
For commercial property owners, it may involve documenting damage to the building, equipment, inventory, and qualifying business operations.
The goal is not to assume that every loss is covered. It is to present the damage accurately and address legitimate differences in scope or valuation under the policy.
Learn more about how public adjusters help New Jersey property owners.
Get Help With an Asbury Park Property Insurance Claim
Property damage can create difficult decisions, particularly when repairs involve older construction, shared building systems, or an operating business.
Main Street Adjusters represents Asbury Park policyholders with fire, flood, water, storm, roof, and commercial property insurance claims.
If your home, condominium, rental property, or business has sustained damage, we can help you review the claim and determine the next steps.
Contact Main Street Adjusters for a free consultation about your Asbury Park property insurance claim.
For other communities we serve, visit our New Jersey Areas Served page.
Frequently Asked Questions
Yes. Main Street Adjusters assists owners of older and historic residential properties. Claims may require careful documentation of original materials, architectural details, structural components, and repairs necessary after a covered loss.
Standard homeowners insurance generally excludes flooding caused by rising surface water or tidal water. Separate flood insurance may provide coverage, subject to policy terms, limits, and exclusions. Other types of water damage may be evaluated under different provisions.
Yes. Main Street Adjusters assists commercial policyholders with property damage claims. Business interruption coverage may also be relevant when covered physical damage causes a qualifying interruption of operations.
A policyholder may be able to retain a public adjuster after receiving an initial estimate or settlement offer. The available options depend on the claim’s status, applicable deadlines, policy requirements, and any settlement agreements already reached.